The question I hear most from buyers is not about prices or rates. It is about themselves. "Am I ready?" And I love that question, because it is the right one to ask. The honest answer is that readiness is two things at once: the numbers a lender checks, and the life you are actually living. Most people are closer than they think. Here is how to tell, plainly.
Your income feels steady
Lenders are not looking for a perfect career story. They want to see a reliable income history, usually about two years of steady work and consistent pay. That can be a salaried job, a business with a healthy track record, or military pay, and buyers who work for themselves simply document their income a little more carefully. If your work feels stable and you can point to a year or two of steady pay, the income side of your ledger is probably in good shape.
Your savings carry the plan
You do not need a giant down payment to buy in Florida. FHA loans work with 3.5% down, VA loans can work with zero, and many conventional loans accept 3%, so the real question is not "how big is my down payment" but "do I have a plan that includes everything." Your plan should cover the down payment, the closing costs, and a cushion for the surprises homeownership brings, because a house is a home and a budget at the same time. If you want the real minimums spelled out, my guide on down payments has them, and if you have a clear plan with a little breathing room, you are more ready than you may believe.
The monthly number fits your life
The most honest test of readiness is the monthly number. Lenders look at your total monthly debts, including your future mortgage payment, and they typically like to see that stay under roughly 43% of your gross income. But the number that matters most is the one you can actually live with. That is where a pre-approval earns its keep: it turns "maybe I can afford it" into a real figure you can plan around. I explain the difference between pre-approval and pre-qualification so you know exactly what to ask for.
Your credit is in a good place
Your credit score decides which loans are available to you and what kind of terms you are offered. The good news is that you can see exactly where you stand before you ever talk to a lender, and small habits, like paying on time and using a modest share of your available credit, move the needle more than people expect. I have a guide with the real score minimums for FHA, conventional, VA, and USDA loans, and it is worth a read before you start.
Your timeline is real
The last ingredient has nothing to do with credit. Buying a home is a commitment of years, not months, and the best buyers have a timeline that fits their life: plans to stay put for a while, a job that is not in flux, and a real reason, whether it is more space for a growing family, a move for work, or the freedom of owning your own walls. When the reason is real and the timing feels right in your gut, that is worth as much as any number.
If you read this and you are not sure where you stand, that is exactly what a first conversation is for. I will look at your numbers with you, honestly and without any pressure, and tell you what is working, what needs a little time, and what to do next, in English or Spanish. When you are ready, reach out. I've got your back.
Ruth Rivera · Broker Associate, Coldwell Banker Realty, Florida
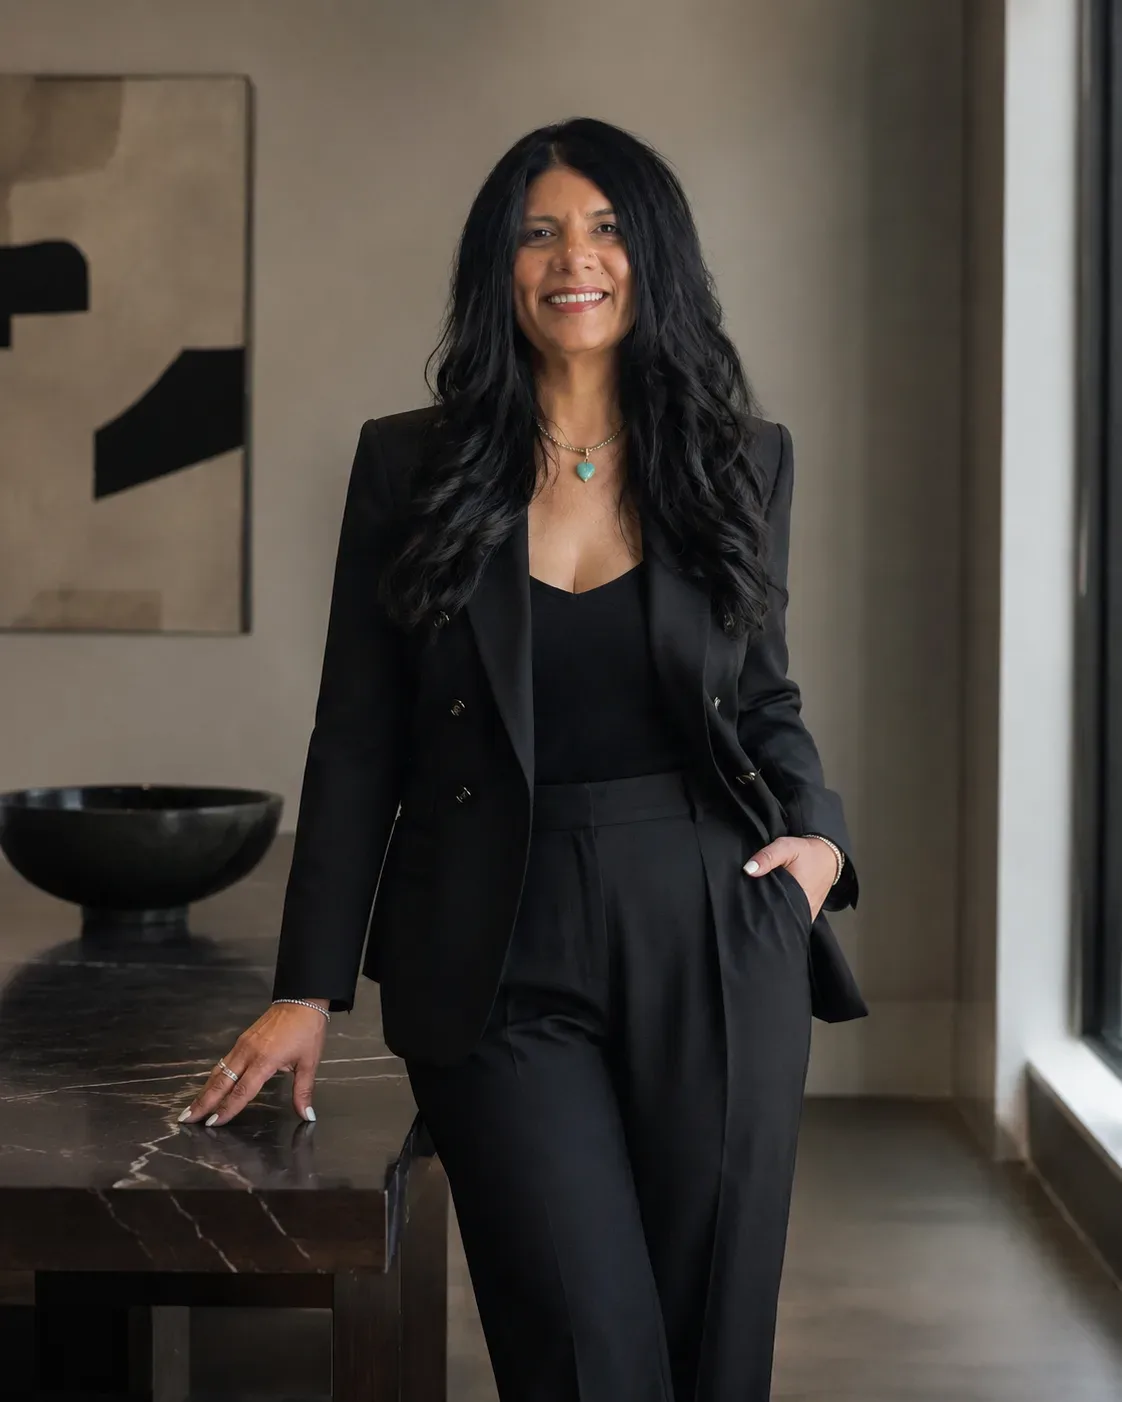
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth