A pre-qualification is a quick estimate based on what you tell a lender. A pre-approval is a verified yes: the lender checks your credit, reviews your income and assets, and hands you a written letter. The difference sounds small, and it decides which offers sellers take seriously.
Pre-qualification: the ten-minute estimate
Pre-qualification is usually a conversation. You share your income, debts, and rough savings, and the lender gives you a ballpark of what you can afford. It is a fantastic budgeting tool for the start of your search, and it costs nothing and involves no credit check in most cases. What it is not is proof: no documents were verified, so sellers and their agents rarely weigh it.
Pre-approval: the verified green light
With a pre-approval, the lender pulls your credit, verifies your income with pay stubs and tax returns, reviews your bank statements and debts, and writes a letter stating the amount and terms you qualify for. It is good for a set window, usually a couple of months, so the best time to get one is before you start serious touring. When the right home shows up, you are ready to move the same afternoon instead of waiting on paperwork.
Why sellers ask for it
In this balanced market, good homes still sell, and sellers want to know the buyer on the other side can actually close. A pre-approval letter from a reputable lender, attached to your offer, separates serious buyers from curious ones without you having to say a word. It is the quiet advantage in every negotiation, and I wrote about the other terms that help offers win here.
How to get pre-approved
A good lender can usually do it in a few days. You will share recent pay stubs, tax returns, and bank statements, answer a few questions, and sign a credit check authorization. It costs nothing to compare lenders, and you are not committing to borrow from any of them; the letter simply confirms what a lender is willing to do. Do this early, not when you have already found the house.
The credit-query worry, handled
Clients often ask me if shopping lenders hurts their score. The good news: when you compare mortgage lenders within a short window, credit scoring treats those mortgage inquiries as a single query, so your score is not punished for shopping. Newer FICO versions group them over 45 days, and some models use 14 (myFICO rate-shopping guidance), which is why we get you comparing lenders in one focused week. The ding from a single grouped inquiry is small, fades within months, and drops off the report within a year.
If you are not sure where to start, tell me where you are in the process and I will point you to lenders I trust and make sure you are set up before we step foot in the first house. The score conversation is part of it too, and I broke down the real credit score minimums here. Ready beats lucky every time, and I want you arriving at your first tour as the buyer sellers say yes to.
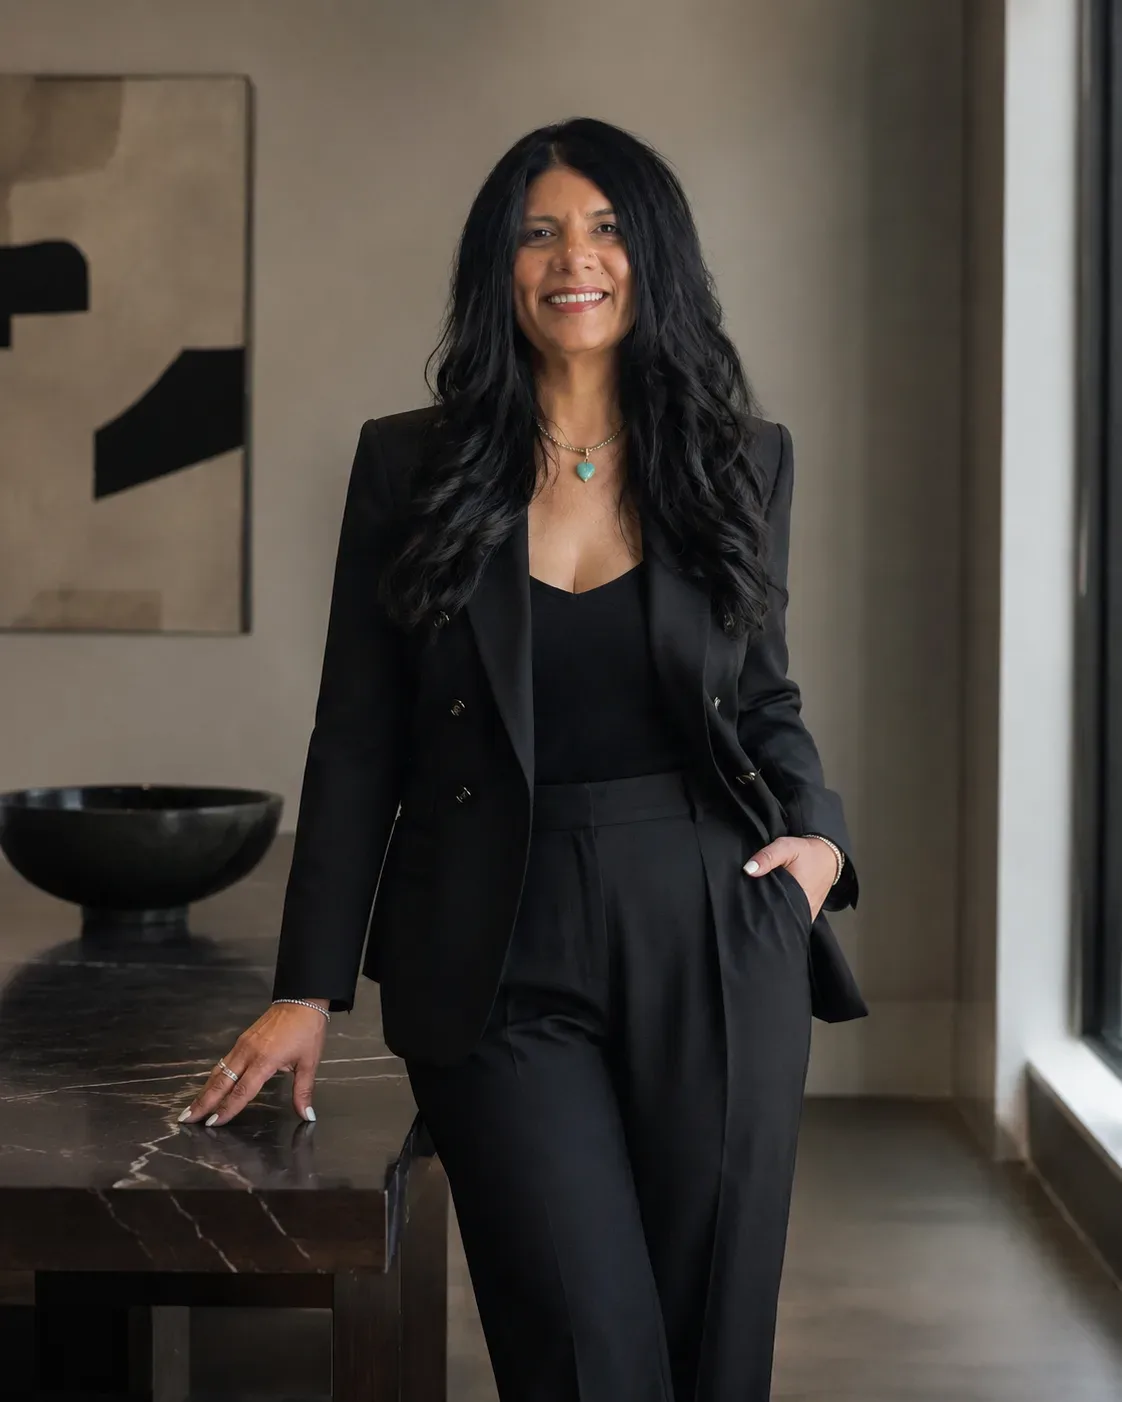
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth