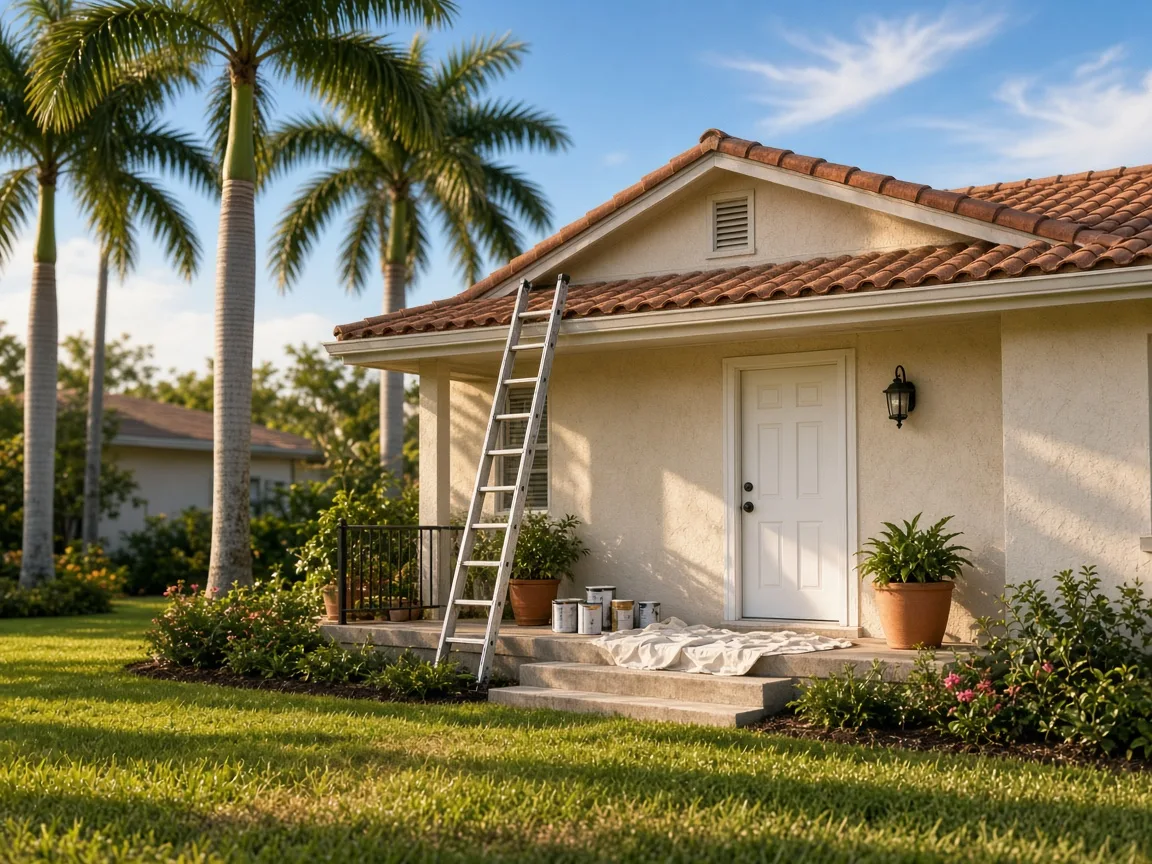
Some buyers fall in love with a home that needs work, and for a long time that meant juggling a mortgage and a separate renovation loan. Today there is a simpler path: renovation mortgages like the FHA 203(k) and Fannie Mae HomeStyle let you roll the purchase price and the remodeling into one loan, with one payment. If you have ever stood in a dated kitchen and seen exactly what it could become, this is the option that makes that vision affordable.
Why one loan beats juggling two
With a renovation loan, the money for both the house and the work is part of a single mortgage. The renovation funds sit in an escrow account and are released in stages, called draws, as the work is completed and inspected. That structure protects everyone: the lender knows the work is really being done, and you are not paying interest on money that has not been spent yet. It also means one closing, one monthly payment, and a much shorter to-do list than managing a separate construction loan.
The FHA 203(k) option
The FHA 203(k) is a government-backed renovation loan, and it comes in two flavors. The Limited 203(k) suits smaller projects, while the Standard 203(k) handles major rehab. A big draw is the low entry point: qualified buyers can put as little as 3.5% down with a credit score around 580 or higher. The trade-off is that the home must be your primary residence, and most of the work needs to be done by licensed, insured contractors rather than your own hands. It is a great fit for a first-time buyer ready to become an owner and put real sweat equity into their home.
The Fannie Mae HomeStyle option
The HomeStyle renovation loan is the conventional, often more flexible choice. The loan is sized off the home's "as-completed" appraised value, meaning your budget reflects what the house will be worth after the work, not before. Down payments can be as low as 3% for qualifying first-time buyers, and it works on primary residences, second homes, and even investment properties. HomeStyle is also a little friendlier to cosmetic upgrades and lets the renovation be finished within roughly six months. For a buyer who wants a broader range of what the work can include, this is usually the option to explore first.
What to expect with either route
Both programs ask for more planning than a standard mortgage. You will gather contractor bids, line up renovation plans, and go through an appraisal based on the finished value. The good news is that this homework protects you from overpaying and keeps the project on a clear budget. Work with a lender who knows renovation lending, and let me help you find a contractor with a track record you can trust. While the work is happening, the standard home inspection still matters, and understanding mortgage insurance helps you plan the monthly picture before you sign.
Who this really fits
A renovation loan is not for everyone, and that is okay. It shines for buyers who want a specific neighborhood or layout, who can handle a few months of construction before their dream kitchen is ready, and who see value in buying a home that needs love at a price that rewards their patience. Florida is full of charming homes with good bones, and this is how a thoughtful buyer turns one into their own. If you are curious whether a fixer-upper and a renovation loan fit your budget and your life, let's talk it through with a lender on the phone and see what the numbers say. I've got your back.
Buying a home should be exciting, not overwhelming. Let's look at the homes with potential in your price range, get real numbers on what the work would cost, and decide together if this is the smart, steady move for you. Not by chance, by design.
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth