PMI, private mortgage insurance, is the monthly premium many buyers pay when they put less than 20% down on a conventional loan. It protects the lender, not you, and the good news is that it is not forever. In most cases it drops off on its own, and you can often ask to cancel it even earlier.
What PMI actually is
When your down payment is under 20%, the lender is carrying more risk, so conventional loans pair with private mortgage insurance to cover part of that risk. It shows up as a line in your monthly payment, and exactly how much depends on your lender, your loan program, and your credit profile. The precise number for your situation is spelled out on the loan estimate your lender gives you, so that document is the one to read line by line.
When you can ask to cancel it
The moment your balance is scheduled to reach 80% of the home's original value, you can request in writing that your servicer cancel PMI. You will need to be current on payments with a good payment history, confirm there are no junior liens, and in some cases provide evidence the home's value has not fallen below the original value, which can mean ordering an appraisal. The Consumer Financial Protection Bureau spells out the full process. One detail clients ask about often: this 80% is measured against the original value of the home, not today's market value, so making extra principal payments is the most direct way to get there sooner.
The automatic rule
For conventional loans closed on or after July 29, 1999, your servicer must end PMI automatically, with no request from you, once your balance is scheduled to reach 78% of the original value, as long as you are current that day. And as a backstop, PMI can never extend past the midpoint of your loan term, 15 years into a 30-year loan, whichever comes first. So the insurance quietly has an expiration date built in, whether you touch anything or not.
The FHA version is different
FHA loans do not carry PMI; they carry a mortgage insurance premium, or MIP, paid to the program itself. The rules there are different, and worth knowing before you choose a loan. On newer FHA loans with a case number assigned on or after June 3, 2013, and a down payment under 10%, the annual MIP lasts for the life of the loan, no matter how much equity you build. With 10% or more down, the annual MIP cancels automatically after 11 years. For many buyers the clean path is refinancing to a conventional loan once you hold about 20% equity, and HUD keeps the current MIP details on its site.
How to make it disappear sooner
Extra principal payments are the friend of anyone with PMI, because they move you toward that 80% mark faster than the original schedule. Some buyers instead pay for an appraisal and ask for cancellation based on today's value, and lenders may accept that route under certain conditions, something we can map together before you close. And remember: none of this means you need 20% down to buy. I wrote about the real minimums for FHA, VA, and conventional loans in plain language, and how pre-approval puts you in the strongest position before you even tour.
The way I see it, PMI is a small price for getting into the right home at the right time, and knowing the exit rules turns it from a mystery into a plan. If you are weighing down payment options and want the math walked through in plain English or Spanish, tell me where you are in the process and I've got your back.
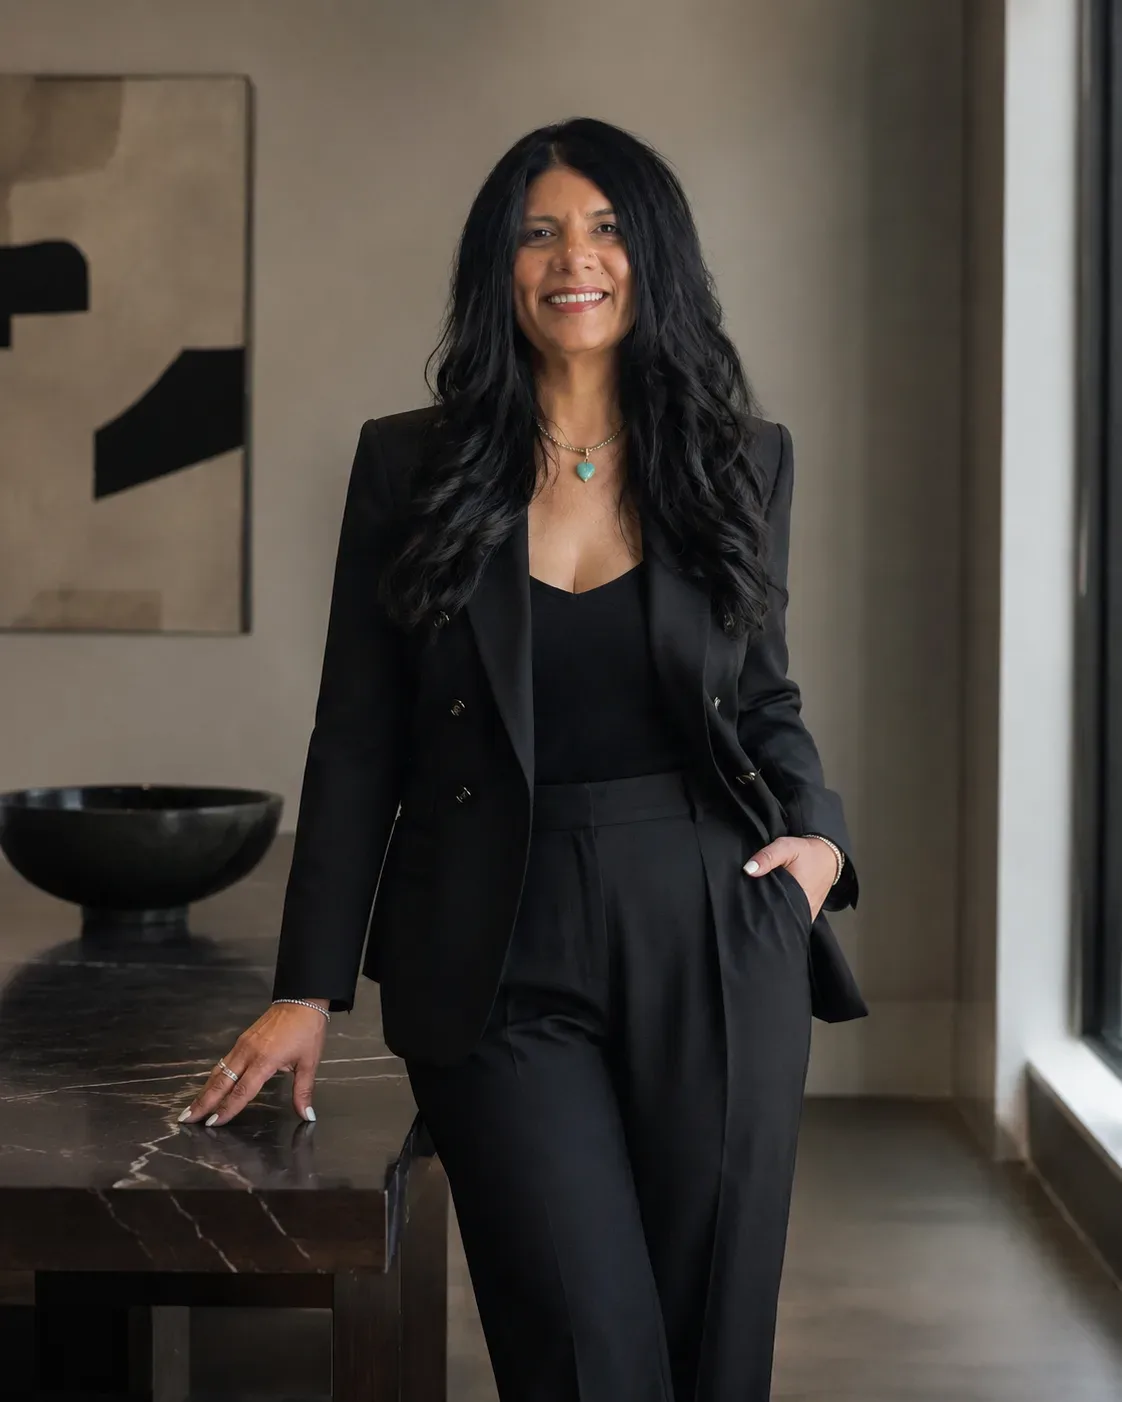
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth