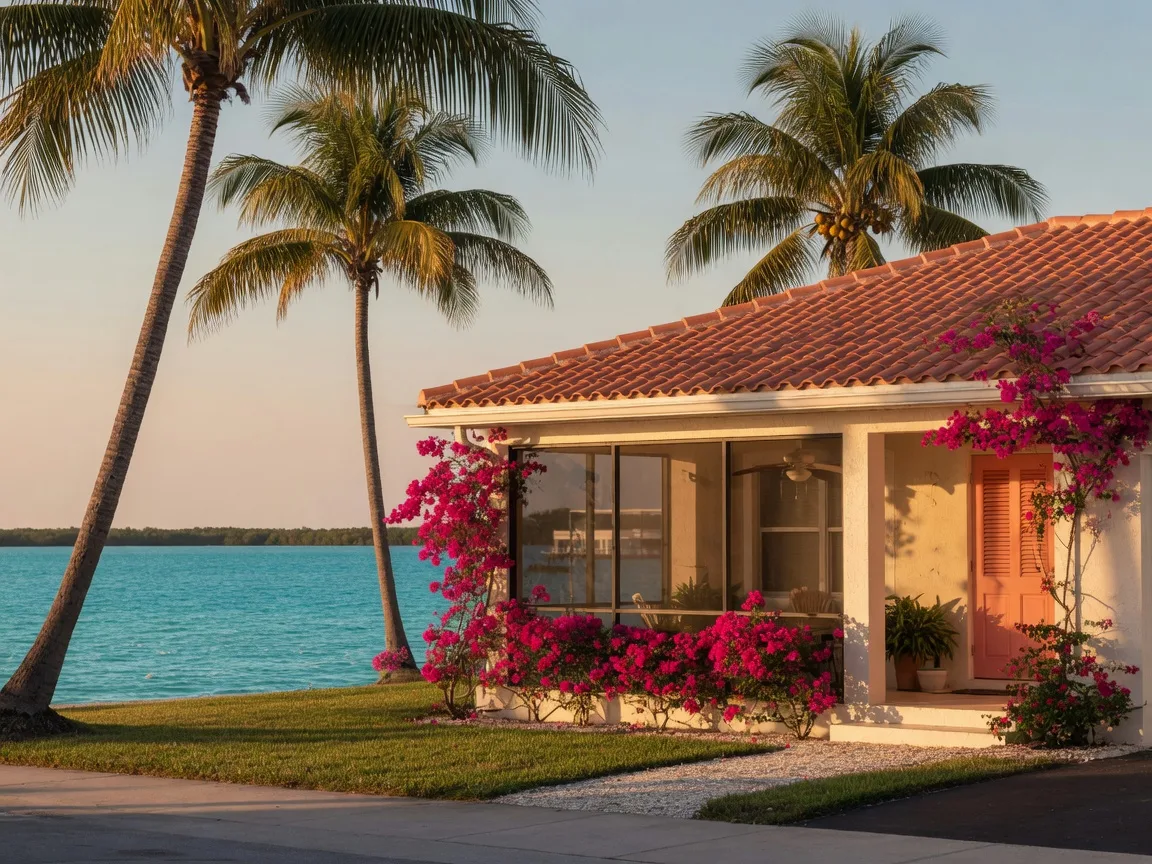
Florida has always drawn people who want a place to escape to, and a second home here can be one of the most rewarding purchases you make. It can also come with layers most buyers do not expect, from how lenders treat second homes to the tax rules that apply when you sell. Let me walk you through what I tell every client who is dreaming of a vacation home, so the dream lands on solid ground.
How lenders see a second home
Lenders treat a second home differently from a primary residence. Because you are carrying two mortgages, the qualification rules are stricter, and the down payment is typically larger, sometimes well above what a first-time buyer would put down. It is worth having the conversation with a lender before you start touring, so you know exactly what your numbers look like. Getting pre-approved for a second home is the same first step as any purchase, and I wrote about why that letter matters here.
Insurance is its own chapter
Home insurance in Florida already deserves attention, and a second home brings its own questions: whether the home is occupied year-round, whether you rent it out, and how close it sits to the coast all shape the policy. I wrote about the questions to ask before you make an offer here. The good news is that a good agent and a good insurance professional will map this out with you before you commit, so there are no surprises at closing.
The tax picture, in plain language
Here is the part most people do not know: the capital gains exclusion that applies when you sell your primary home does not apply to a vacation home. Under IRS rules, you can generally exclude up to $250,000 of gain (up to $500,000 for married couples filing jointly) only on the sale of your main home, and only if you have owned and lived in it for at least two of the five years before the sale (IRS Publication 523). A second home that never became your main home does not qualify, and if you rent it out, the tax picture gets more detailed still. None of this should scare you off; it is simply a conversation to have with your tax professional before you buy, so you go in with your eyes open.
Who will take care of it?
A vacation home needs someone to check on it, whether you are two hours away or two states away. Many owners hire a property manager, especially if they plan to rent the home out when they are not using it. That is a real monthly cost and a real decision, and it deserves a spot in your budget from day one. Some buyers choose a condo or a managed community precisely because the maintenance is handled for them, and I wrote about the questions to ask before buying a condo here.
Use it before you buy it
The best advice I give vacation home buyers is to spend real time in the area first. Visit in different seasons, talk to neighbors, and see what the neighborhood feels like on a quiet Tuesday, not just a holiday weekend. A home that feels perfect in July can feel very different in January. When you find the right one, you will know, and I will be there to make sure the offer, the inspection, and the closing all protect you.
A second home is a big decision, and it should feel exciting, not overwhelming. I have helped buyers from all over the country and from Puerto Rico and Latin America find their Florida place, and I would love to help you think through yours. The right home, chosen on purpose, is worth every bit of the planning.
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth