An appraisal is simply an independent, licensed opinion of what a home is worth, ordered by your lender to protect its loan. It is not a home inspection and it is not a magic number; it is one careful professional’s read, built from recent sales that actually closed. Once you know what it is, it stops being scary, so here is the plain-language version I give every buyer, along with what happens on the rare day the number comes in low.
Who orders it, and why
Your lender orders the appraisal before your loan can close, because the bank wants to be sure the home is worth what it is lending against. You typically pay for it as part of your closing costs, and you get a copy of the report. If you have not seen one yet, my guide to closing costs in Florida shows where it fits in the bigger picture.
What the appraiser actually looks at
The heart of an appraisal is comparables: homes similar in size, age, and condition that closed nearby recently, not homes still sitting on the market. On top of that, the appraiser walks the property to weigh layout, upgrades, condition, lot size, and location. The appraiser is not judging your taste; they are comparing apples to apples, with the market doing the talking.
When the number comes in low
First, breathe. A low appraisal is more common than people think, and it is almost never the end of the road. The usual paths, in the order we try them: request a reconsideration of value with better comparables, which your agent gathers and submits; renegotiate the price with the seller; cover the gap yourself if you comfortably can; or use your appraisal contingency to walk away cleanly and keep looking. Every one of those is a conversation, and you want an agent who runs it calmly on your behalf.
When it comes in high
Sometimes the report confirms your offer was a good one, and you start with equity on day one. For sellers, the flip side matters just as much: the appraiser works from closed sales, which is why pricing from today’s data, not last year’s, protects your sale from appraisal surprises later.
Talk about appraisal risk before the offer
The best time to think about the appraisal is before you write the offer, when we can look at what similar homes have actually closed for, shape the offer to the market, and decide which contingencies stay in. Surprises are for parties. If you want the full tour of everything between an accepted offer and the keys, that guide covers it all.
If the word appraisal has you worried, or you just want to understand the process before you start, ask me. I have walked buyers and sellers through every version of this conversation, in English and Spanish, and a straightforward answer has never hurt anyone.
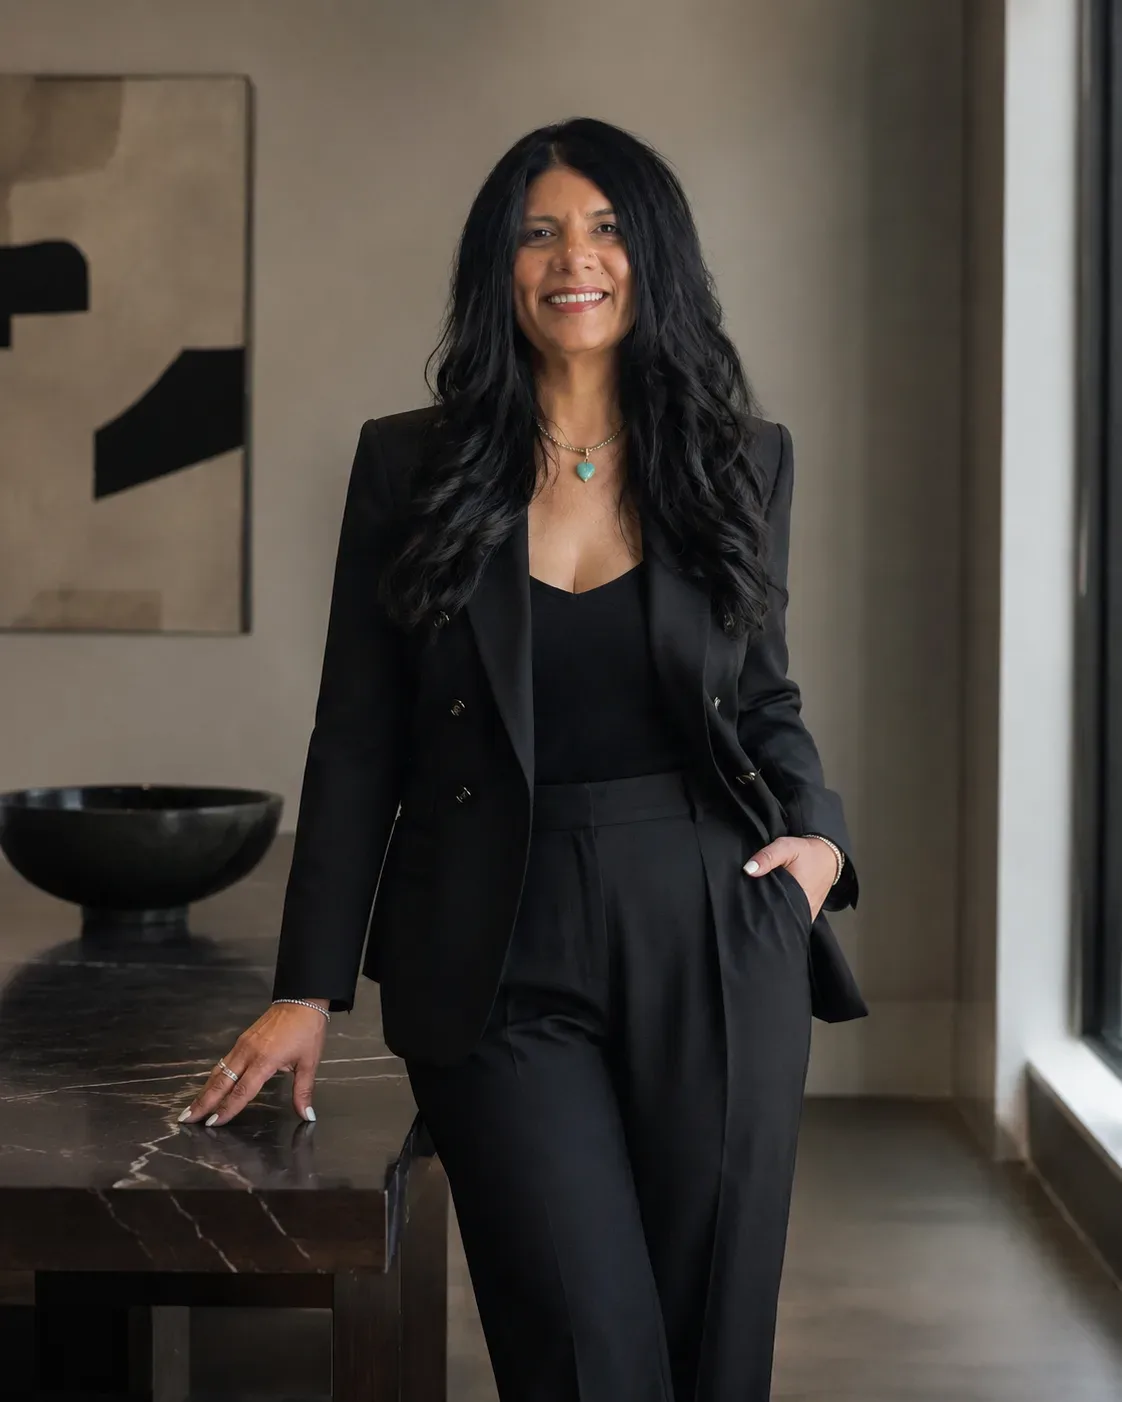
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth