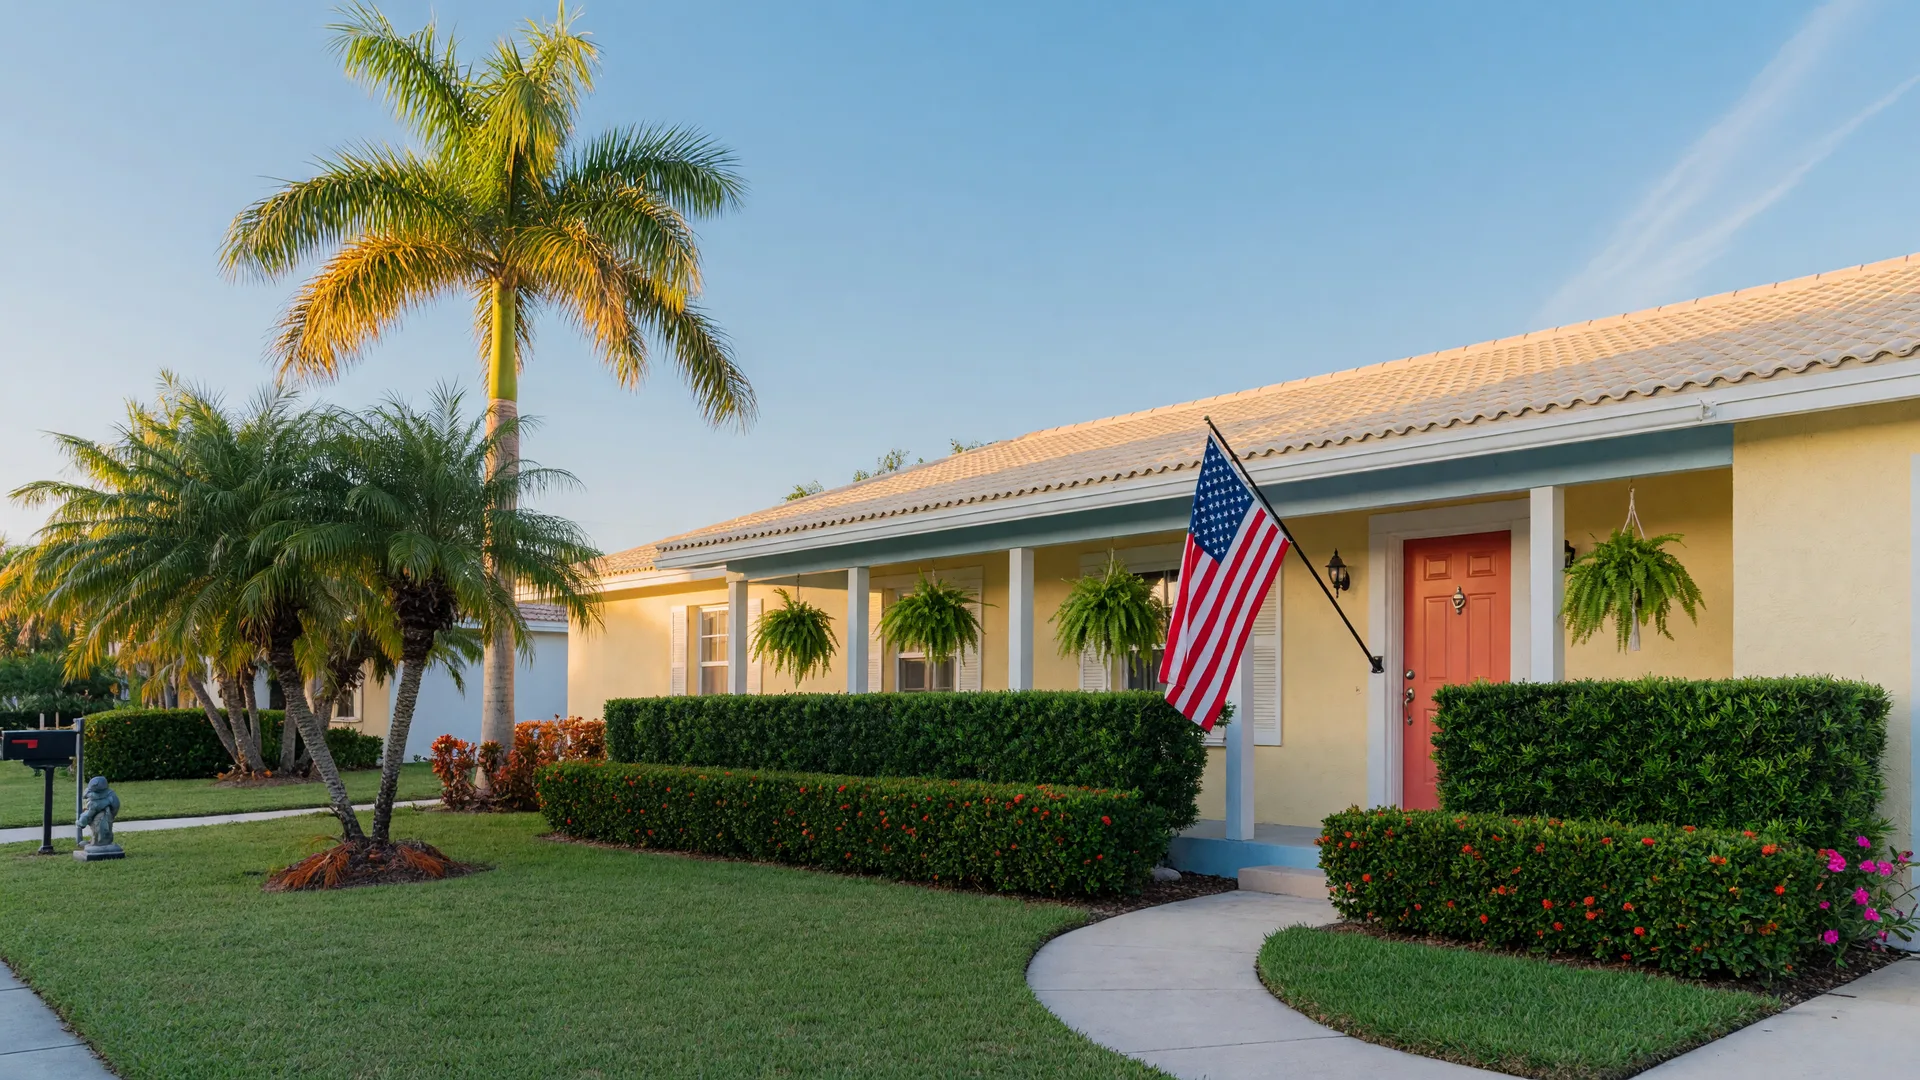
Serving asks a lot of you, and the VA home loan was built to give something back. If you have served or are serving, there is a good chance you have earned the right to buy a home in Florida with zero down payment and no monthly mortgage insurance, and I want you to know exactly how it works. It is one of the strongest home-buying benefits available, and I love helping the men and women who served use it well.
The benefit, in plain language
Qualified veterans and service members can buy with no down payment at all. There is no monthly private mortgage insurance to add to your payment, which is a real difference compared with most other loans. Rates on VA loans are competitive, and the benefit is designed to be reusable, so it is there for you again down the road if you decide to buy another home. That combination, no down payment and no monthly insurance, is why so many of my veteran clients start their search with real confidence.
The funding fee, explained
There is one cost to know about: the VA funding fee. It is a one-time fee on most purchase loans, and for a first-time user buying with less than 5% down it is 2.15% of the loan amount, with lower rates when you put 5% or 10% down. Here is the part that surprises people pleasantly: the fee can be financed into the loan, so you do not have to hand it over out of pocket. And many veterans do not pay it at all, including those receiving VA disability compensation for a service-connected disability, along with some surviving spouses. Your lender will tell you exactly where you stand before you commit to anything.
Your Certificate of Eligibility
Every VA loan starts with a Certificate of Eligibility, the document that proves to the lender you qualify for the benefit. Getting yours is easier than it sounds: the fastest path is often to have your lender pull it electronically, or you can request it online through VA.gov, where your service records usually let them issue it on the spot. Your DD Form 214 is the key document you will lean on. It is a small step, and it unlocks the whole program.
The rule to plan around
One requirement shapes every VA purchase: the home has to be your primary residence. You certify your intent to occupy it, and you are generally expected to move in within about 60 days of closing. There are thoughtful exceptions, such as deployment or a permanent change of station, where a spouse or dependent can satisfy the occupancy for you. It is a simple rule that protects the program, and it is easy to plan around once you know it. If a down payment question brought you here, this pairs well with my guide on whether you really need 20% down.
How I help veterans buy in Florida
I work around your schedule, including evenings and video calls if you are stationed far from the home you are buying, and I speak English and Spanish, because the clearest conversations are the ones in the language you think in. I have guided veterans from first conversation to the keys, and the questions in the early talks are often the same ones first-time buyers ask me most. If you are ready to see what your benefit can do in Florida, reach out and we will map out your path, honestly and without pressure. You earned this, and it should work as hard for you as you worked for your country.
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth