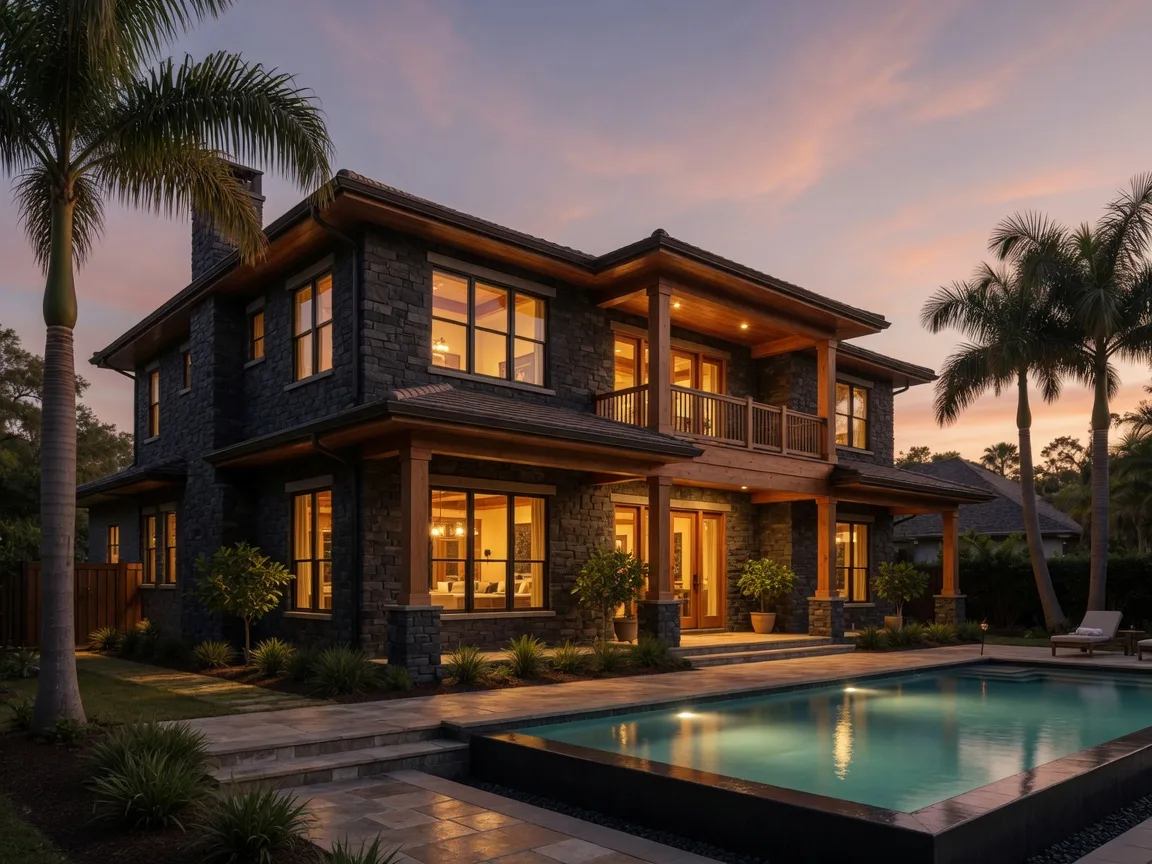
Most people think of moving up as two separate transactions: sell mine, then buy theirs. In practice it is one careful dance, and the families who do it well treat it that way from the very first conversation. When your next home is funded by your current one, the two deals are wired together, and the magic is in the sequencing, the contingencies, and the dates. Here is how I walk clients through getting both sides right.
Start with the math on both sides
On the same day we draw two columns. One shows what your sale needs to produce: the proceeds after the mortgage payoff, the closing costs, and the prep that helps you sell well. The other shows what your purchase needs: the down payment, the closing costs, and a comfortable buffer for the move itself. When sale proceeds fund the purchase, those two columns tell us which side drives the timeline. Very few people build this equation before they talk to a lender, and it is the single best way to avoid surprises later.
The three ways to sequence the dance
Selling first puts you in the strongest position as a buyer: cash in hand and an offer with no strings attached. The cost is moving twice or spending a few weeks in temporary housing. Buying first lets you move once, but you carry two homes and need financing to bridge the gap, and you sell from a position where every week counts. Then there is the third path: making your purchase offer contingent on selling your current home. It is the safest option, but in a balanced market the seller of the next home may not wait for yours if another strong offer arrives. The contingency only works when it is written as a plan, with a defined window to sell and a backup financing route if the window closes.
The closing dates: the seam where plans break
Two closing dates that were never introduced to each other mean a moving truck with nowhere to go, two mortgages at once, or weeks of “so where do we sleep?” When I coordinate both sides, I negotiate the two calendars at the same time: the closing date of your sale and the closing date of your purchase can land the same day or just days apart. And if the move needs a soft landing, there is a graceful bridge called a rent-back: you stay in your sold home for a set number of days after closing under a written agreement. It is common, it is negotiated, and it gives the whole family room to breathe.
Keep both offers strong
The buyer of your home wants certainty, and so does the seller of the next one. An offer with a solid pre-approval, a real down payment, and flexible dates competes far better than one loaded with conditions. Being a seller does not make you a weaker buyer when we present it right: you walk in with a plan, not with a need. And on the sale side, we give your home the same treatment, honest pricing, small repairs handled, and a story that helps the next family picture themselves there, so your sale closes on time and your purchase can follow.
Getting both sides right is not luck; it is choreography, and I have danced it many times. If you are ready to trade up, let us sit down and map the two sides on one calendar, the numbers, the dates, and the backup plans, before you commit to anything. That order is what protects you.
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth