The most common myth I hear from first-time buyers is that you need a giant pile of cash before you can even start looking. The truth, more often than not, is that help with the down payment exists, with real numbers behind it. Florida Housing Finance Corporation, the state's housing agency, administers down payment and closing cost assistance in every one of Florida's 67 counties. Here is how the programs actually work.
How the assistance works, in one sentence
Every program pairs a second mortgage with a Florida Housing 30-year fixed-rate first mortgage, originated through approved lenders across the state, and the assistance rides on top of an FHA, VA, USDA, or conventional first loan. That is the whole structure: one purchase, one closing, two loans, and the second one is the help.
FL Assist: up to $10,000 with no monthly payment
The most popular option is a 0% interest, deferred second mortgage of up to $10,000 toward your down payment and closing costs. There is no monthly payment at all. The balance is repaid when you sell, refinance, pay off or transfer the first mortgage, or stop living in the home. It works with FHA, VA, USDA, and conventional first mortgages, which makes it the most flexible place to start the conversation.
FL HLP Second: $12,500 with a small monthly payment
If you need a bit more, the Florida Homeownership Loan Program second mortgage offers up to $12,500 at 3% interest, fully amortized over 30 years. On the full amount that works out to roughly $52.70 a month, a modest line in the budget. Any remaining balance is due when you sell, refinance, or move out.
The forgivable options: HFA Preferred PLUS and HFA Advantage PLUS
These are the ones clients get most excited about, and for good reason. The assistance equals 3%, 4%, or 5% of the first mortgage amount, at 0% interest, and it is forgiven 20% per year over five years of living in the home. Stay five years, and the help is gone entirely, not repaid. These options are only available with a conventional HFA Preferred or HFA Advantage first mortgage, which is the trade-off to talk through with your lender.
Hometown Heroes: for the people who keep Florida going
Under the Live Local Act, income-qualified teachers, healthcare workers, first responders, veterans, and other eligible workforce borrowers can get assistance equal to 5% of the first mortgage, capped at $35,000 with a $10,000 minimum, as a deferred second with no monthly payment. Funding is allocated in cycles and can be fully committed, so timing genuinely matters. If your work fits the list, this one is worth asking about early.
The fine print that makes it work
Income and purchase price limits vary by county, and a credit score around 640 is typically the floor for FL Assist. You will also complete a state-approved homebuyer education course, which I can point you to and which most buyers find genuinely useful. The standard programs define a first-time buyer as someone who has not owned a primary residence in the past three years, while Hometown Heroes is open to qualifying workforce borrowers beyond first-timers.
Where to check the current details
Program terms are refreshed with each funding cycle, so the numbers above reflect the published terms today and your lender will confirm what is live for your exact file. The official source is Florida Housing's homebuyer overview, with the Hometown Heroes details published separately. Always plan around the version your lender confirms.
Combine the help with the reality
Down payment assistance pays part of the way, not all of it, so pair it with the real minimums: FHA loans work with 3.5% down and many conventional loans with 3%, which is far from the 20% people assume, and my guide to how much you really need walks through it. Then add the closing costs on top, and your lender puts the whole picture on one page.
Help like this exists for exactly the people it was built for, and I have seen it change the math for real families. If you want to know whether one of these programs fits your situation, call me. I will connect you with the right lender, help you line up the documents, and walk with you every step, in English or Spanish, and I've got your back.
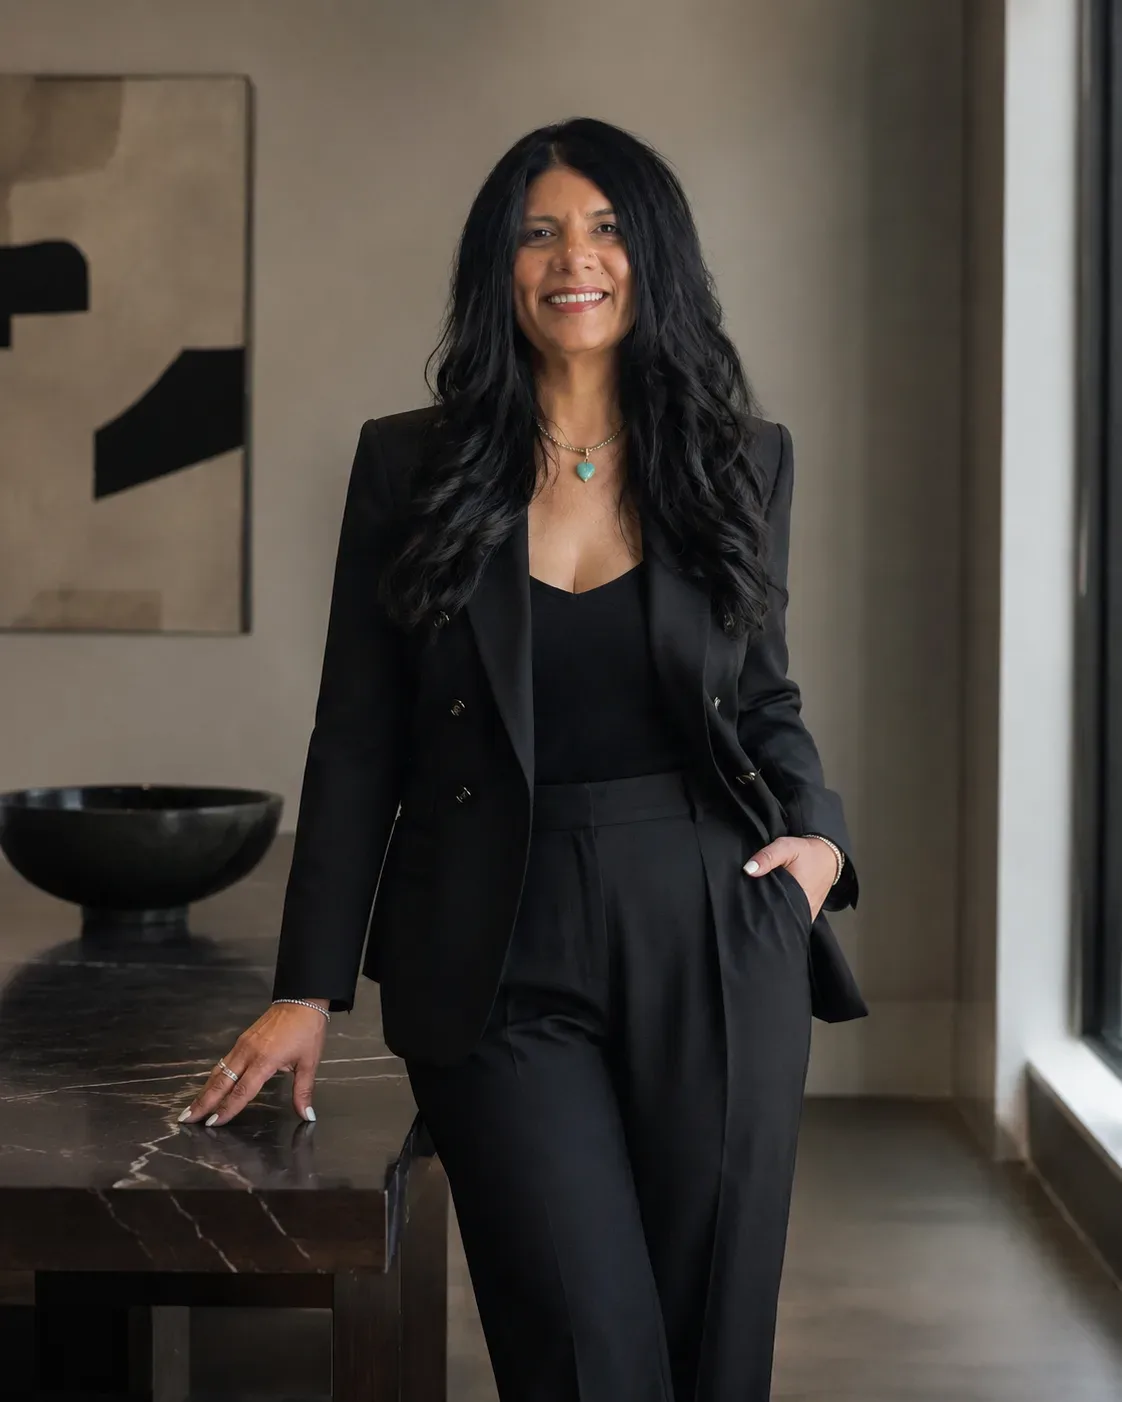
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth