The honest answer is that selling a home in Florida costs more than the price on the sign suggests, and knowing the full picture before you start is what turns a good result into a great one. The pieces fall into three buckets: what you spend getting the home ready, what you pay at the closing table, and what you carry while the sale happens. None of it has to be a surprise. All of it can be planned.
The prep money: a short list, not a renovation
Most sellers do not need a renovation; they need a short, smart list. The repairs that show up in every inspection, a deep clean, fresh paint on the doors people touch, and tidy landscaping. These are the items that make a buyer comfortable offering more, and they are the ones I walked you through in my guide on what sellers should fix before listing. Budget for them early, and none of them will feel like a surprise later.
At the closing table: the seller's costs
Florida sellers pay a set of costs at closing that buyers never see: the state's documentary stamp tax, which is calculated on the sale price; title insurance and the title search; recording fees; property taxes prorated to your closing date; and, in a community with an HOA, the association's transfer and estoppel fees. Florida title companies break these line items out clearly, and taken together with the commission, seller costs typically run in the 6% to 10% range depending on your price, your county, and your contract. That is exactly why a smart listing strategy looks at net proceeds, not the sticker price.
Concessions: a choice, not a loss
Sometimes the strongest offer includes the seller helping with the buyer's closing costs or a rate buydown. That is not money lost; it is a strategy, and often a smarter one than a price cut. I explain the trade-offs in my piece on seller concessions, but the short version is this: a deal that closes on time for a slightly lower cost is worth more than a deal that falls apart over a number.
The costs nobody prints on the flyer
Holding costs are real: your mortgage, property taxes, insurance, and utilities keep running while the home is on the market. Moving costs and temporary housing add up when buying and selling do not line up perfectly. And one bright spot: under the IRS primary residence rule, if you have owned and lived in the home two of the past five years, you can exclude up to $250,000 of gain from taxes as a single filer, and up to $500,000 for married couples filing jointly. A good chunk of your profit can be tax-free, which is worth knowing long before you list.
How to keep more of your proceeds
Price with current data, not nostalgia, because pricing mistakes cost more than any fee. Fix the short list, stage with light and space, treat concessions as strategy, and ask for a written net proceeds estimate before you ever sign a listing agreement. Sellers who see the whole map make calmer, stronger decisions.
Selling should never be a guessing game. When we sit down, we map every line of your costs early, so the number you walk away with is the number you planned for. English or Spanish, and I've got your back. Not by chance, by design.
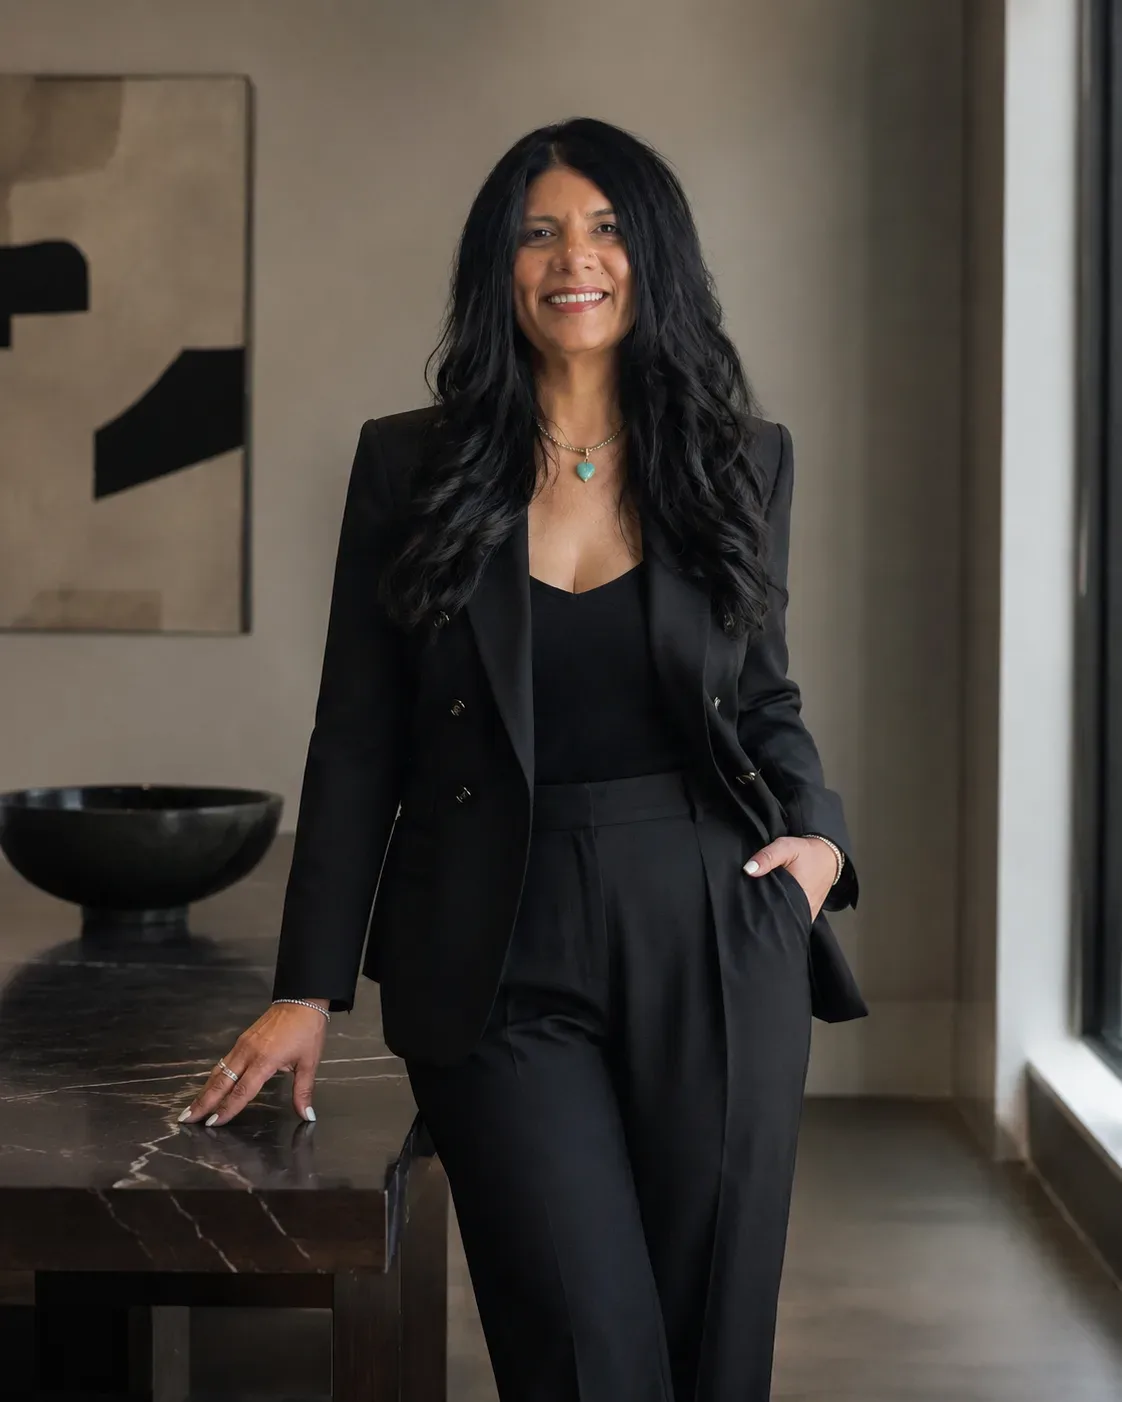
Written by
Ruth Rivera
Broker Associate with Coldwell Banker Realty, in real estate since 1992, with offices across Florida. 1000+ homes sold, licensed in Florida (BK3168285). Bilingual, English and Spanish.
Have a question about your specific situation?
Ruth answers personally, in English or Spanish. She's got your back.
Ask Ruth